Category: Investing

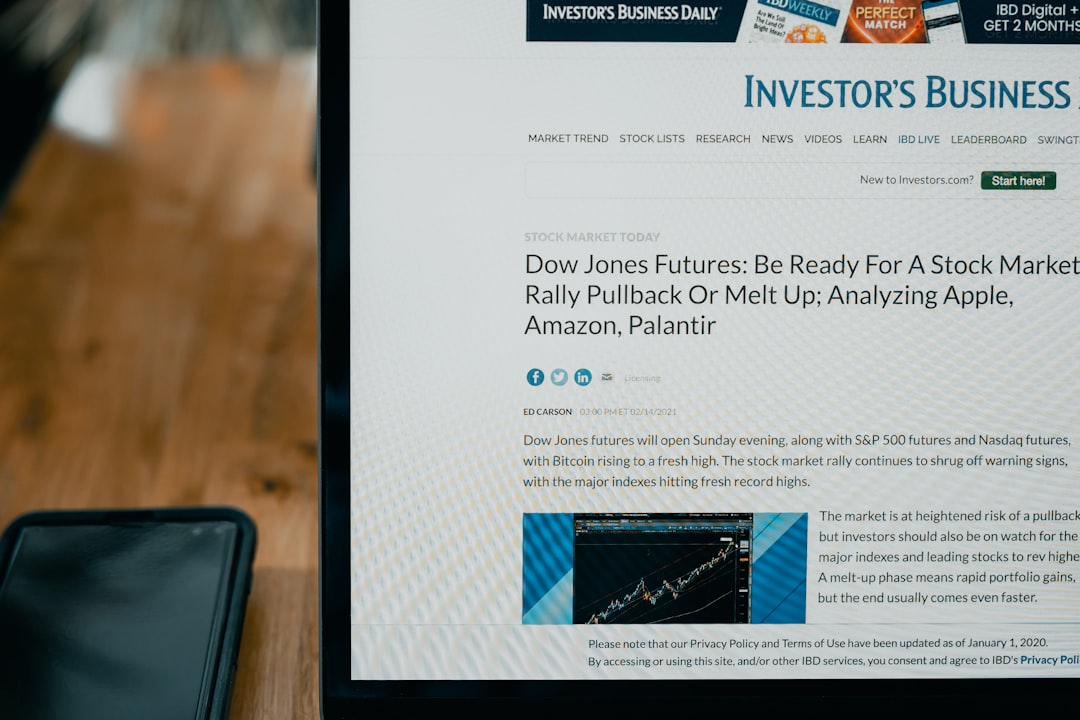
  • Understanding Minimalist Investing for New Investors 2026

    Understanding Minimalist Investing for New Investors 2026

    In the rapidly evolving landscape of personal finance, minimalist investing strategies are gaining traction, especially among new investors in 2026. As the complexity of financial markets grows, many are seeking simplicity and efficiency in their approach to building wealth. This trend reflects a broader desire for clarity and sustainability, aligning perfectly with the ethos of Calm Wealth Blog.

    What is Minimalist Investing?

    Minimalist investing focuses on simplifying the investment process to reduce stress and enhance clarity. The idea is to streamline your portfolio by concentrating on a few key investments that align with your financial goals. This method not only reduces the time and energy spent managing a complex array of assets but also helps in making more informed and deliberate investment decisions.

    The Principles of Minimalist Investing

    At its core, minimalist investing rests on a few foundational principles:

    • Simplicity: Choosing straightforward investment options like index funds or ETFs that provide broad market exposure.
    • Focus: Concentrating on a limited number of investments to better understand and manage them.
    • Cost-efficiency: Minimizing fees and expenses that can eat into returns over time.
    • Long-term perspective: Avoiding the temptation to frequently trade and instead focusing on long-term wealth accumulation.

    Benefits for New Investors

    New investors can particularly benefit from minimalist investing strategies. The simplified approach makes it easier to get started without feeling overwhelmed by the myriad of choices. Here’s how it can help:

    Reduced Complexity

    By focusing on a streamlined portfolio, new investors avoid the paralysis that often comes from too many options. For example, instead of navigating through numerous stocks, a new investor might choose a single diversified index fund that covers the S&P 500.

    Lower Costs

    Minimalist investing typically involves low-cost investment vehicles. Index funds and ETFs generally have lower expense ratios compared to actively managed funds. This cost-saving aspect can significantly enhance net returns over time.

    Ease of Management

    Managing fewer investments means spending less time monitoring the market and more time focusing on other aspects of financial planning. This ease of management can be particularly appealing to those who are new to investing and may not have the time or expertise to manage a complex portfolio.

    Implementing Minimalist Investing

    To implement minimalist investing strategies effectively, consider the following steps:

    Define Your Goals

    Start by clearly defining your financial goals. Are you saving for retirement, a home, or a child’s education? Your goals will guide your investment choices and risk tolerance.

    Choose the Right Investment Vehicles

    Select investment options that align with your goals. For most, this means choosing a mix of low-cost index funds or ETFs. For example, a simple portfolio might include a total stock market index fund, a bond fund, and an international fund.

    Regularly Review Your Portfolio

    While minimalist investing requires less frequent monitoring, it’s still important to review your portfolio periodically. Ensure that your investments are still aligned with your goals and make adjustments as needed.

    Stay Disciplined

    The simplicity of minimalist investing can be undermined by emotional decision-making. Stick to your plan, avoid the temptation to chase market trends, and focus on your long-term goals.

    Real-World Example — The Case of the “Three-Fund Portfolio”

    A popular example of minimalist investing is the “Three-Fund Portfolio,” which consists of a U.S. stock index fund, an international stock index fund, and a bond index fund. This simple structure provides broad diversification and is easy to manage. An investor following this strategy might allocate 50% to the U.S. stock fund, 30% to the international stock fund, and 20% to the bond fund, adjusting these ratios based on their risk tolerance and investment horizon.

    Conclusion — Embrace Simplicity for Long-Term Success

    As new investors navigate the complexities of the financial world, minimalist investing strategies offer a refreshing alternative. By focusing on simplicity, cost-efficiency, and long-term planning, investors can achieve sustainable financial growth. In 2026 and beyond, these principles will remain crucial for those seeking to build wealth mindfully and effectively.

    Photo by Tech Daily on Unsplash
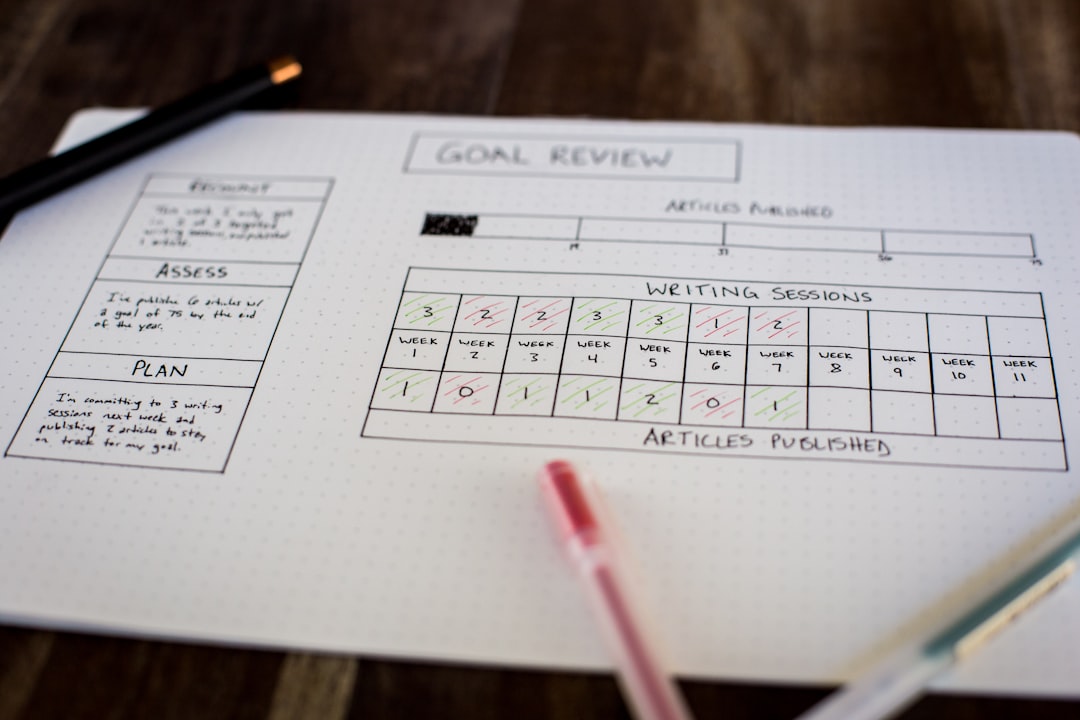
  • Zero-Based Budgeting vs Envelope System for Mindful Savers

    Zero-Based Budgeting vs Envelope System for Mindful Savers

    In the evolving landscape of personal finance, choosing the right budgeting method can significantly impact your financial goals. For mindful savers looking to build sustainable wealth, understanding the nuances of zero-based budgeting vs envelope system is essential. This comparison targets individuals who aim to manage their finances with intention and clarity, aligning with the values of simplicity and discipline that define 2026’s financial strategies.

    Understanding Zero-Based Budgeting

    Zero-based budgeting, a method that gained popularity in corporate finance, requires you to allocate every dollar of your income to specific expenses, savings, or investments until your budget equals zero. This approach promotes active decision-making by demanding justification for every expense, making it ideal for those who want to gain granular control over their finances.

    Exploring the Envelope System

    The envelope system, often associated with physical cash management, involves dividing your income into categories, each represented by an envelope. Once the money in an envelope is spent, no more can be used for that category until the next budgeting period. This tactile method encourages discipline and makes abstract spending limits tangible, appealing to those who prefer a hands-on approach.

    Zero-Based Budgeting vs Envelope System — Key Comparisons

    Flexibility and Adaptability

    Zero-based budgeting offers flexibility by allowing adjustments to be made as priorities shift. If an unexpected expense arises, you can reallocate funds from other categories. In contrast, the envelope system can be less adaptable, particularly if you use cash. Once funds in an envelope are depleted, you’re forced to wait until the next period unless you’re willing to ‘borrow’ from another envelope, which can blur the discipline lines.

    Level of Control

    For those seeking detailed control, zero-based budgeting is unmatched. By accounting for every dollar, it ensures that your spending aligns precisely with your financial goals. The envelope system, while providing control through tangible limits, may not offer the same level of detail unless meticulously managed, especially in digital form.

    Ease of Implementation

    Implementing zero-based budgeting can initially be time-consuming as it requires careful planning and tracking. However, digital tools and apps have simplified this process. The envelope system is straightforward to start, especially in its traditional cash form. However, maintaining it digitally can become complex without the right tools, potentially leading to confusion if not well-organized.

    Suitability for Different Spending Habits

    Zero-based budgeting suits those who want to scrutinize their spending habits and are comfortable with digital tools for tracking and adjustments. It’s particularly effective for individuals with variable income streams who need to adjust allocations regularly. The envelope system benefits those who respond well to visual and physical cues, making it effective for controlling discretionary spending in categories like dining out or entertainment.

    Psychological Impact

    Zero-based budgeting can feel empowering due to the high level of control it offers, but it can also be overwhelming if not managed carefully. The envelope system provides immediate feedback—when an envelope is empty, it clearly signals to stop spending. This can be a powerful deterrent against overspending but may also feel restrictive if not balanced with flexibility.

    Verdict

    For those who thrive on detail and require a high degree of control, zero-based budgeting is likely the better choice. It suits individuals who enjoy leveraging technology to maintain tight financial oversight. Conversely, if you prefer simplicity and a more tactile approach to managing money, the envelope system might be more suitable. It’s perfect for those who benefit from visual cues and a straightforward method to curb spending.

    Both zero-based budgeting and the envelope system offer unique advantages for mindful savers. Choosing between them depends largely on your personal financial habits and preferences. While zero-based budgeting provides comprehensive control, the envelope system offers simplicity and tactile reinforcement. As you assess zero-based budgeting vs envelope system, consider which aligns with your lifestyle and financial goals, helping you to build wealth mindfully and sustainably.

    Photo by Isaac Smith on Unsplash

  • How to Implement Mindful Wealth Building Without Overwhelm

    How to Implement Mindful Wealth Building Without Overwhelm

    Building wealth mindfully in today’s fast-paced world can feel like a daunting task. Many people find themselves overwhelmed by the myriad of financial advice available, unsure of how to proceed without adding stress to their lives. Fortunately, mindful wealth building strategies offer a way to grow your financial health while maintaining balance and peace of mind.

    To implement mindful wealth building without feeling overwhelmed, the key is to start small and stay consistent. By focusing on achievable goals and adopting a few simple practices, you can steadily build long-term wealth.

    Understanding Mindful Wealth Building Strategies

    Mindful wealth building strategies involve making conscious, deliberate decisions about your finances. This approach emphasizes awareness and intentionality, helping you avoid the stress of impulsive financial choices. By being present in your financial journey, you can better align your money habits with your personal values and goals.

    What You Need to Get Started

    • Clarity on Financial Goals: Understand what you’re aiming for financially, whether it’s saving for retirement, buying a home, or achieving financial independence.
    • A Simple Budget: Create a basic budget that tracks your income and expenses. Tools like YNAB or Mint can help.
    • A Journal for Reflection: Use a journal to document your financial journey, noting your intentions and reflecting on your progress.
    • Commitment to Consistency: Be prepared to make small, regular efforts towards your financial goals.

    Step-by-Step Guide to Implement Mindful Wealth Building

    1. Set Clear Financial Intentions: Begin by identifying specific, achievable financial goals. Write these down in your journal and revisit them often to keep them at the forefront of your financial decisions.
    2. Develop a Mindful Budget: Craft a budget that reflects your priorities. Allocate funds for necessities, savings, and discretionary spending. Review it monthly to adjust as needed, ensuring it aligns with your mindful wealth building strategies.
    3. Practice Habit Stacking: Incorporate small, positive habits into your daily routine. For example, automate savings by setting up a monthly transfer to a high-interest savings account. Over time, these habits can significantly impact your financial health.
    4. Reflect Regularly: Spend a few minutes each week reflecting on your financial decisions. Use your journal to note what worked, what didn’t, and how you felt about your choices. This reflection helps you stay aligned with your goals.
    5. Simplify Your Investments: Choose investment strategies that are easy to understand and manage. Index funds or ETFs offer low-cost, diversified options that don’t require constant monitoring.

    Common Mistakes and How to Avoid Them

    • Overcomplicating the Process: Trying to do too much at once can lead to burnout. Start with simple changes and gradually add complexity as you become more comfortable.
    • Ignoring Emotional Triggers: Be aware of emotional spending triggers and have strategies in place to deal with them. This might include taking a pause before making purchases or discussing major financial decisions with a trusted friend.
    • Neglecting Self-Care: Financial health is closely linked to overall well-being. Ensure that you’re not sacrificing your mental or physical health in the pursuit of wealth.

    Embrace the Journey

    By implementing these mindful wealth building strategies, you create a sustainable financial life that aligns with your values and goals. This approach reduces stress and empowers you to make thoughtful, informed decisions. As you continue on this journey, remember that the aim is not perfection but progress. By staying committed to these practices, you’ll find yourself on a steady path to financial growth without the overwhelm.

    Photo by Markus Winkler on Unsplash

  • Best Free Habit Tracking Tools for Financial Goals 2026

    Best Free Habit Tracking Tools for Financial Goals 2026

    In the journey toward financial independence, building consistent, productive habits is crucial. Whether you’re just starting your financial journey or looking to enhance your existing strategies, finding the best free habit tracking tools can make a significant difference. By keeping your financial goals in check, these tools help ensure that your wealth-building efforts are consistent and effective.

    If you’re pressed for time and need a quick recommendation, consider trying Habitica. This tool gamifies your habit-tracking experience, making it engaging and fun to meet your financial goals.

    Discover the Best Free Habit Tracking Tools

    1. Habitica

      If you enjoy games and need a little extra motivation, Habitica might be the perfect fit for you. By turning your financial goals into quests and challenges, this tool transforms mundane tasks into an adventure. You earn points and rewards for completing your tasks, which can keep you motivated to stick to your financial plans. Habitica is especially great for those who thrive on competition and collaboration, as you can join parties and fight monsters together.

    2. Loop Habit Tracker

      Loop Habit Tracker is simple yet powerful, offering an easy-to-use interface for Android users. This app focuses on long-term habit formation, providing analytics and graphs to help you understand your progress over time. Its minimalist design ensures that you stay focused on tracking your financial habits without getting distracted by unnecessary features.

    3. Strides

      Strides is a versatile habit tracker available for iOS users. With its flexible goal-setting options, you can track anything from daily savings goals to monthly investment check-ins. The app’s dashboard gives you a clear view of your progress, helping you quickly see which areas need more attention. Its notification reminders can keep you on track, making it easier to stay disciplined with your financial habits.

    4. Coach.me

      For those who want a little extra guidance, Coach.me offers both habit tracking and access to a community of coaches. While the basic habit tracking is free, you can choose to hire a coach if you need more personalized support. This feature can be particularly beneficial if you’re trying to build complex financial habits or need accountability to stay on track.

    5. TickTick

      TickTick is more than just a task manager. It’s also a robust habit tracker. Its integration with calendars and reminders makes it a great choice for those looking to align their financial tasks with their daily schedules. By organizing your tasks and habits in one place, you can manage your financial goals alongside other personal and professional commitments.

    Comparing the Tools

    Each of these tools offers unique features that cater to different needs:

    • Habitica: Best for those who enjoy gamification and social interaction.
    • Loop Habit Tracker: Ideal for Android users looking for simplicity and analytics.
    • Strides: Perfect for iOS users who need flexible goal-setting options.
    • Coach.me: Excellent for individuals seeking additional coaching support.
    • TickTick: Suitable for those who want to integrate task management with habit tracking.

    Choosing the right tool depends on your personal preferences and specific financial goals. If you need a fun, engaging way to track habits, Habitica might be your best bet. For those who prefer a more straightforward approach, Loop Habit Tracker or Strides could be ideal. If you benefit from additional guidance, consider Coach.me. Finally, if you like keeping everything organized in one place, TickTick can help align your financial habits with your overall daily agenda. Whatever your choice, these tools can support you on your path to building a stable financial future.

    Photo by Brett Jordan on Unsplash

  • General Guide to Mindful Financial Decisions in 2026

    General Guide to Mindful Financial Decisions in 2026

    As we navigate the complexities of personal finance in 2026, integrating mindfulness into our financial decisions is more important than ever. The concept of mindful financial decisions 2026 serves as a guiding principle for individuals seeking not only financial stability but also a sense of peace and purpose in their money management practices. This comprehensive guide offers insights into how mindfulness can influence your financial choices, leading to improved financial health and well-being.

    Understanding Mindfulness in Financial Decisions

    Mindfulness, often associated with meditation and mental well-being, involves being present and fully engaged in the current moment without judgment. When applied to financial decisions, mindfulness encourages a deliberate and thoughtful approach, promoting clarity and reducing impulsive behaviors. This mindset shift can lead to more intentional spending, saving, and investing, aligning actions with long-term financial goals.

    Mindful Spending in 2026

    With a plethora of consumer choices and marketing influences at every turn, mindful spending becomes a crucial strategy. The practice involves questioning the necessity and value of each purchase, ensuring it serves a purpose beyond immediate gratification. By integrating mindfulness, individuals can reduce unnecessary expenditures and financial stress, fostering a healthier relationship with money.

    Practical Steps for Mindful Spending

    • Pause Before Purchasing: Before making a purchase, take a moment to reflect on its necessity and how it aligns with your financial goals.
    • Create a Spending Plan: Outline your financial priorities and allocate your resources accordingly, preventing impulsive deviations.
    • Reflect on Purchases: Regularly review your expenditures to identify patterns and opportunities for improvement.

    Mindful Saving — Building a Financial Cushion

    Saving mindfully involves more than just setting aside a portion of your income. It requires a conscious effort to understand your savings goals and the motivations behind them. Establishing a robust financial cushion provides security against unforeseen events, reducing anxiety about the future.

    Strategies for Mindful Saving

    • Set Clear Goals: Define specific, measurable savings objectives, such as building an emergency fund or planning for retirement.
    • Automate Savings: Use technology to automate transfers to savings accounts, ensuring consistency without effort.
    • Reassess Regularly: Periodically evaluate your savings strategy to adapt to changes in income or expenses.

    Mindful Investing — Balancing Risk and Reward

    Investment decisions are inherently fraught with uncertainty and risk. A mindful approach to investing involves careful consideration of both risk and reward, aligning investments with personal values and long-term goals. This method encourages thoughtful analysis and helps investors avoid emotional decision-making.

    Implementing Mindful Investing

    • Research Thoroughly: Before investing, conduct comprehensive research to understand the potential risks and rewards.
    • Diversify Thoughtfully: Spread investments across different asset classes to manage risk while pursuing growth.
    • Reflect on Values: Choose investments that align with your ethical and personal values, such as sustainable or socially responsible options.

    Creating Sustainable Wealth Through Mindfulness

    Mindfulness extends beyond immediate financial decisions to encompass broader wealth-building strategies. Creating sustainable wealth involves establishing passive income streams that are ethical and aligned with your values. By focusing on quality and long-term potential, you can ensure stable and consistent income growth.

    Building Mindful Passive Income Streams

    • Evaluate Opportunities: Assess potential passive income options based on their alignment with your long-term goals and values.
    • Invest in Quality: Prioritize investments in high-quality, reliable income-generating assets.
    • Monitor Consistently: Regularly review and adjust your passive income strategies to ensure ongoing alignment with your objectives.

    Aligning Financial Independence with Personal Values

    Financial independence is not just about accumulating wealth but doing so in a way that resonates with your core beliefs. Mindfulness can guide you in aligning your financial journey with personal values, fostering a more fulfilling and meaningful financial life.

    Strategies for Value-Aligned Financial Independence

    • Clarify Your Values: Identify your core values and how they influence your financial decisions.
    • Plan Holistically: Develop a comprehensive financial plan that integrates personal values at every stage.
    • Reflect and Adjust: Continuously reflect on your journey and make necessary adjustments to stay true to your values.

    As we move forward in 2026, the practice of mindful financial decisions becomes a vital tool for achieving financial wellness. By incorporating mindfulness into spending, saving, investing, and wealth-building strategies, individuals can cultivate a balanced and harmonious financial life. This approach not only enhances financial health but also enriches personal well-being, making each financial decision a step towards a more mindful and fulfilling future.

    Photo by Brett Jordan on Unsplash

  • FAQs About Mindfulness in Personal Finance

    FAQs About Mindfulness in Personal Finance

    In the bustling world of personal finance, integrating mindfulness can be a significant shift in how we manage money. The concept of mindfulness in personal finance FAQs is gaining traction, offering clarity for those aiming to reduce financial stress and improve their money habits. This guide tackles common questions about mindful financial practices, providing insights that align spending, saving, and investing with personal values.

    Understanding Mindfulness in Personal Finance FAQs

    What is mindfulness in personal finance?

    Mindfulness in personal finance means being fully aware of your financial habits and decisions. It involves paying attention to how you spend, save, and invest money, ensuring that these actions align with your long-term goals. This approach helps reduce impulsive decisions that can lead to financial stress.

    How can mindful spending improve my financial health?

    Mindful spending focuses on making intentional purchases that align with your values and financial goals. By evaluating whether a purchase truly adds value to your life, you can avoid unnecessary expenses and reduce financial anxiety. This practice encourages living within your means while enjoying the things that matter most.

    Can mindfulness help me save more effectively?

    Yes, mindfulness can significantly enhance your saving habits. By recognizing the emotional triggers that lead to impulsive spending, you can redirect those funds into savings. Setting specific, meaningful saving goals and regularly reviewing them can keep you motivated and on track.

    What role does mindfulness play in investing?

    Mindful investing involves a balanced approach that considers both risk and reward, aligning investments with your personal values. By thoughtfully analyzing investment opportunities and their impact, you can make decisions that not only grow your wealth but also support ethical and sustainable practices.

    How can I integrate mindfulness into my budgeting process?

    To incorporate mindfulness into budgeting, start by creating a flexible plan that adapts to life changes. Regularly review your budget to ensure it supports your goals and values. This practice helps maintain a healthy balance between saving, spending, and investing, leading to long-term financial stability.

    What are practical ways to practice mindfulness in my daily financial life?

    Begin with small steps, like pausing before making a purchase to consider its necessity. Reflect on your financial decisions at the end of each day to understand their impact. Consistently practicing these habits fosters a deeper awareness of how your financial choices affect your overall well-being.

    Can mindfulness really help reduce financial stress?

    Absolutely. Mindfulness encourages a focus on the present moment, helping you manage financial stress by breaking down overwhelming tasks into manageable actions. It allows you to address financial challenges methodically rather than reactively, leading to a more peaceful and structured financial life.

    How does mindfulness align with achieving financial independence?

    Mindfulness supports financial independence by fostering disciplined saving and investing habits that are in harmony with personal values. It helps prioritize long-term goals over short-term desires, ensuring that every financial decision contributes meaningfully to your journey toward independence.

    Are there any common misconceptions about mindfulness in personal finance?

    One misconception is that mindfulness requires significant time and effort. In reality, it involves simple shifts in awareness and routine. Another is that it limits enjoyment, but mindful practices aim to enhance life satisfaction by aligning financial actions with personal values.

    Incorporating mindfulness into personal finance can transform your financial journey by promoting intentionality and reducing stress. By addressing these FAQs about mindfulness in personal finance, you now have actionable insights to start enhancing your financial habits. Begin applying these principles today to align your financial life with your core values and long-term goals.

    Photo by Jakub Żerdzicki on Unsplash

  • Opinion — Why Mindful Investing Will Dominate 2026

    Opinion — Why Mindful Investing Will Dominate 2026

    As we move toward 2026, the concept of mindful investing is poised to become the dominant strategy for savvy investors. This growing trend emphasizes the importance of aligning one’s investments with personal values, long-term goals, and a deep awareness of financial ecosystems. By incorporating mindfulness into investment strategies, investors can not only enhance their financial returns but also contribute to a more sustainable and ethical economy.

    The Rise of Mindful Investing in 2026

    Mindful investing is not just a passing trend. It represents a fundamental shift in how individuals approach their financial decisions. In the fast-paced, often volatile world of investing, this approach offers a way to slow down and make more thoughtful choices. For many, the allure of quick profits through speculative investments is losing its sheen, replaced by a desire for stability and ethical growth. This shift is particularly relevant in the context of global challenges such as climate change, social inequality, and economic instability.

    Why Mindful Investing Matters

    Incorporating mindfulness into investing practices is crucial for several reasons. First, it aligns investments with personal values, which can foster a sense of purpose and satisfaction beyond financial gains. This alignment can encourage deeper engagement and commitment to investment strategies. Moreover, mindful investing has the potential to reduce stress. By focusing on long-term goals and ethical considerations, investors can avoid the anxiety of daily market fluctuations and impulsive decision-making.

    Additionally, the mindful investing trend in 2026 is expected to drive significant capital toward sustainable and socially responsible companies. As more investors prioritize environmental, social, and governance (ESG) criteria, this can lead to a stronger emphasis on corporate accountability and ethical business practices. This shift is not only beneficial for the planet and society but also for investors who seek stable, long-term growth.

    Supporting Evidence for Mindful Investing

    One compelling reason for the rise of mindful investing is the increased availability of data and tools that enable investors to evaluate the ethical impact of their portfolios. Platforms that provide insights into ESG factors are becoming more sophisticated, allowing investors to make informed decisions that align with their values.

    Additionally, case studies of investors who have adopted mindful investing strategies reveal promising outcomes. For example, portfolios that emphasize sustainable practices often demonstrate resilience during market downturns. This resilience is attributed to the strong fundamentals of companies that prioritize long-term value over short-term profit.

    Challenges and Counter-Arguments

    Critics of mindful investing might argue that it limits investment opportunities and could potentially reduce returns. They suggest that focusing too heavily on ethical considerations might lead to missed opportunities in high-growth sectors that do not yet meet ESG criteria. However, this perspective often overlooks the evolving nature of these sectors and the increasing demand for sustainable practices.

    Furthermore, while some may view mindful investing as a niche market, the growing consumer demand for transparency and ethical responsibility is likely to expand opportunities within this space. As more companies adapt to these expectations, investors stand to benefit from early involvement in industries poised for long-term growth.

    The Verdict on Mindful Investing

    The mindful investing trend in 2026 represents a profound evolution in how we approach our financial futures. By prioritizing ethics and long-term stability, investors can achieve not only financial success but also contribute to a more equitable and sustainable world. As this approach gains traction, it will likely redefine the landscape of investing, making it an essential consideration for forward-thinking investors.

    In conclusion, as you contemplate your investment strategies, consider the benefits of incorporating mindfulness into your financial decisions. With its potential to provide both emotional and financial rewards, mindful investing is more than a trend. It’s a transformative approach that promises to shape the future of finance. Embrace this shift and align your investments with your values and the broader goals of society.

    Photo by Brett Jordan on Unsplash

  • Case Study — Achieving Financial Independence Through Mindfulness

    Case Study — Achieving Financial Independence Through Mindfulness

    Imagine achieving financial independence through mindfulness, a journey that not only promises economic freedom but also aligns with your core values and emotional well-being. This case study explores how one individual transformed their financial life by integrating mindful practices, leading to a more balanced and stress-free path to wealth.

    The Starting Point

    Meet Laura, a 35-year-old marketing professional living in Seattle. Like many, she felt trapped in the cycle of paycheck-to-paycheck living, despite earning a decent salary. Her financial habits were driven by impulse, often leading to end-of-month stress and little to no savings. Laura realized that her approach to money was reactive rather than proactive, and this was affecting her overall happiness and sense of security.

    Understanding the Challenge

    The obstacle Laura faced was multifaceted. It wasn’t just about overspending. It was about the underlying anxiety and lack of control that her financial situation imposed on her life. With a student loan debt of $30,000 and minimal savings, Laura’s challenge was to find a way to manage her finances that didn’t feel restrictive or overwhelming. The stress of financial instability was affecting her personal relationships and career satisfaction.

    Implementing Mindful Strategies

    Laura’s solution began with education. She started reading about financial independence through mindfulness, eager to integrate these principles into her life. Her first step was creating a detailed budget that prioritized needs over wants. But unlike traditional budgeting methods, Laura focused on understanding the ‘why’ behind her spending habits. She attended workshops and practiced techniques like mindful meditation to become more aware of her financial triggers.

    Laura also embraced the concept of intentional spending. She asked herself questions like “Does this purchase align with my long-term goals?” before making any financial decision. This approach helped her cut down unnecessary expenses by 20% within the first three months.

    Investing was another area where Laura applied mindfulness. She shifted from impulsive stock purchases to a disciplined investment strategy, focusing on index funds aligned with her values. This not only diversified her portfolio but also reduced the emotional rollercoaster she previously experienced with market fluctuations.

    Measurable Outcomes

    In just two years, Laura’s mindful approach led to significant changes. She paid off her student loans entirely, built an emergency fund worth six months of living expenses, and grew her investment portfolio by 40%. Most importantly, her stress levels decreased, and her satisfaction with life increased, as she felt more in control and aligned with her values.

    Lessons Learned

    • Align Spending with Values: Understanding what truly matters to you can help eliminate unnecessary expenses.
    • Practice Self-awareness: Regularly reflect on your financial habits to identify triggers and areas for improvement.
    • Prioritize Education: Equip yourself with knowledge about mindful financial practices and investment strategies.
    • Set Clear Goals: Define what financial independence looks like for you to create a roadmap that is both motivating and achievable.
    • Embrace Flexibility: Life changes, and so should your financial plan. Be open to adjusting your strategies as needed.

    What This Means for You

    Laura’s journey illustrates that financial independence through mindfulness is not only achievable but also profoundly enriching. By integrating mindful practices, you can transform your relationship with money, reduce stress, and align your financial journey with your personal values. Whether you aim to pay off debt, build wealth, or simply find peace of mind, mindfulness provides a sustainable path to financial prosperity. As you consider your financial future, remember that the key lies in conscious decision-making and aligning your financial habits with what truly matters to you.

    Photo by Markus Winkler on Unsplash

  • Mindful Saving vs Automatic Saving — Which is Better for You?

    Mindful Saving vs Automatic Saving — Which is Better for You?

    Choosing between mindful saving and automatic saving can be a pivotal decision in managing your finances effectively. Both strategies offer distinct benefits and cater to different financial habits. As more people strive for financial wellness, understanding these approaches can help you align your saving habits with your personal goals. Whether you’re seeking more control over your finances or looking for an effortless way to save, this comparison will illuminate which path is better suited for your needs.

    Understanding Mindful Saving vs Automatic Saving

    Mindful Saving relies on conscious decision-making and self-awareness. It involves regularly reflecting on your financial goals and making intentional choices about where to allocate your money. This approach encourages you to be present with your spending and saving habits, fostering a deeper connection with your financial decisions. It’s ideal for those who prefer to have hands-on control and enjoy the act of actively managing their money.

    Automatic Saving, on the other hand, sets in motion a system where a predetermined amount is transferred from your checking account to your savings account at regular intervals. This “set it and forget it” strategy minimizes the need for constant decision-making, making it easier to save consistently without the temptation of spending that money. It’s particularly beneficial for individuals who struggle to set aside money regularly or who prefer a more hands-off approach.

    Mindful Saving vs Automatic Saving — A Head-to-Head Comparison

    Involvement and Control

    Mindful saving offers a high degree of involvement, which can be empowering for those who enjoy being actively engaged in their financial decisions. It requires you to routinely assess your financial status and make decisions based on your current and future needs. This involvement can lead to a greater sense of control and satisfaction, knowing that each decision aligns with your personal values.

    Automatic saving minimizes the need for active involvement. Once set up, it runs in the background, freeing you from the need to make frequent saving decisions. This can be particularly appealing to those with busy lifestyles or those who find the discipline of regular saving challenging.

    Flexibility and Adaptability

    Mindful saving is inherently flexible. It allows you to adapt your saving strategies as your financial situation or goals change. If you experience a sudden increase in expenses or decide to save for a new goal, you can easily adjust your saving patterns in response.

    Automatic saving is less flexible in that it requires manual adjustments if your financial circumstances change. While you can alter the saving amounts or frequency, it doesn’t automatically adapt to changes in your income or expenses.

    Consistency and Discipline

    Mindful saving relies heavily on personal discipline. The success of this approach depends on your ability to consistently make intentional saving decisions. While it can foster strong financial habits, it may not provide the same level of consistency if you struggle with self-discipline.

    Automatic saving excels in consistency. By automatically transferring funds at regular intervals, it ensures that savings occur consistently, regardless of daily spending habits. This can be particularly advantageous for those who find it difficult to save regularly on their own.

    Psychological Impact

    Mindful saving can have a positive psychological impact by enhancing your financial awareness and promoting a sense of accomplishment. Actively choosing where your money goes can lead to greater satisfaction and less stress about finances.

    Automatic saving reduces the cognitive load associated with saving decisions by automating the process. This can alleviate stress and make saving feel less burdensome, but it may also lead to a disconnect from your financial goals if you’re not regularly reviewing them.

    Verdict — Which One is Right for You?

    If you value control and enjoy the process of actively managing your finances, mindful saving may be the better option. It allows you to tailor your saving strategy to fit your personal goals and lifestyle changes. However, if you seek a simple and consistent saving method that requires less daily involvement, automatic saving might be more suitable. It ensures that your savings grow without the need for constant attention.

    Final Thoughts on Mindful Saving vs Automatic Saving

    Ultimately, the choice between mindful saving and automatic saving depends on your personal preferences and financial goals. Both strategies can effectively contribute to your financial wellness when aligned with your needs. Consider your lifestyle, discipline, and desire for control when deciding which approach to adopt. By understanding the nuances of each method, you can make an informed decision that supports your journey towards financial independence and peace of mind.

    Photo by Towfiqu barbhuiya on Unsplash

  • How to Create a Mindful Spending Plan Without Sacrificing Fun

    How to Create a Mindful Spending Plan Without Sacrificing Fun

    Creating a mindful spending plan without sacrificing fun is a goal many of us share. It’s about striking a balance between being financially responsible and enjoying life’s pleasures. If you’ve ever felt guilty about splurging or worried about your financial future, this guide is for you. Let’s explore how to have a budget-friendly lifestyle that doesn’t compromise on joy.

    To create a mindful spending plan without sacrificing fun, focus on aligning your purchases with your values and priorities while allowing space for enjoyment. This approach ensures your financial health while keeping your life fulfilling.

    Understanding Your Financial Landscape

    Before diving into the specifics of a mindful spending plan, it’s essential to understand the current state of your finances. Knowing where you stand helps you make informed decisions about where your money should go.

    1. Assess Your Income and Expenses: Start by listing all your sources of income and tracking your expenses for a few months. Use budgeting apps or simple spreadsheets to categorize your spending and identify areas for improvement.
    2. Identify Non-Negotiable Expenses: These include rent, utilities, groceries, and other essential bills. Knowing these costs helps you determine how much flexibility you have with discretionary spending.
    3. Set Clear Goals: Define what financial success looks like for you. Whether it’s saving for a trip, paying off debt, or building an emergency fund, having clear goals will guide your spending choices.

    Creating Your Mindful Spending Plan Without Sacrificing

    With a clear understanding of your financial situation, you can now build a spending plan that aligns with your values. Here’s how to do it effectively:

    1. Prioritize Your Values: Reflect on what truly matters to you. Is it traveling, dining out, or investing in hobbies? Allocate funds to these areas while cutting back on less meaningful expenses.
    2. Implement the 50/30/20 Rule: Use this simple budgeting framework to allocate 50% of your income to essentials, 30% to wants, and 20% to savings and debt repayment. Adjust the percentages based on your personal priorities.
    3. Set Fun Money Aside: Designate a specific amount each month for guilt-free spending. This could be for spontaneous outings or treating yourself, ensuring that you’re living joyfully without financial stress.
    4. Practice Conscious Spending: Before making a purchase, ask yourself if it brings you joy or supports your goals. This practice helps avoid impulse buys and aligns spending with your values.
    5. Review and Adjust Regularly: Life changes, and so should your budget. Set monthly check-ins to review your spending plan, celebrate successes, and adjust where necessary.

    Common Pitfalls and How to Avoid Them

    Navigating the world of mindful spending isn’t without its challenges. Here are some common mistakes and how to avoid them:

    • Over-Restricting Yourself: While it’s important to save, being too strict can lead to burnout. Allow some flexibility and treat yourself occasionally to maintain balance.
    • Ignoring Small Purchases: These can add up quickly and derail your budget. Track every expense, no matter how small, to maintain control over your finances.
    • Not Involving Your Partner or Family: Financial decisions affect everyone in your household. Ensure everyone is on board with the plan to avoid conflicts and ensure consistency.

    Living a Balanced Financial Life

    By creating a mindful spending plan without sacrificing fun, you’re setting yourself up for both financial stability and personal satisfaction. This approach allows you to enjoy the present while planning for the future. With conscious spending and regular adjustments, you can live a rich and fulfilling life without financial guilt.

    Photo by Katie Harp on Unsplash